Barely a week goes by without a headline about the housing crisis. Depending on how and what data is presented homes are either unaffordable, unsellable, or in the wrong areas. Most of this coverage is national, and a national average provides little insight to local house prices, on the street you live on or the one you would like to live on.
There is a better way to make sense of it, and it is free.
A tool worth bookmarking
HM Land Registry publishes the UK House Price Index, the official measure of house prices, built from completed sales. Its online tool lets you pick a local authority, London borough, county or region and chart how prices have moved over any period you choose. For England and Wales, local figures go back to January 1995, and you can split them by detached, semi-detached, terraced houses, and flats. You can also split by first-time buyer or those buying without a mortgage.
Local house prices are what matter
In the year to July 2026, average prices rose 4.9% in the North East but fell 3.3% in London, the eleventh month in a row of falling London prices. Southwark, where Wealth Spring is based, and where Elliot lives has been roughly flat over the time period.
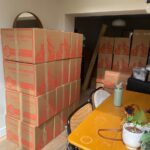
When you next read a housing story, I would encourage you to spend five minutes checking what the data says for your area, and the relevant type of property. It puts the headlines in your local context. To keep the theme of ‘personal’ going I have included a photo of our house before our move last year.
The inflation lens
The index measures prices in pounds, and isn’t adjusted for inflation, which certainly affects the picture. In January 2020 the average Southwark home cost around £580,000. Consumer prices have risen by about 32% since, so to keep pace with inflation that home would need to fetch roughly £766,000 today. The actual average is £572,000, a real-terms fall of about a quarter.
Over the last year alone, consumer prices rose 2.9%, so even the UK average rise of 1.4% was a small fall in real terms, and in London the real fall was about 6%.
If property fails to keep pace with inflation it highlights the vulnerability of a financial plan that purely relies on downsizing, or property sales.
What the numbers don’t show
Price data only tells part of the story. It doesn’t capture mortgage affordability, which depends on interest rates as much as prices. Nor does it reflect rising service charges on leasehold flats, or council tax increases. These all affect what buyers are willing to pay and can move prices away from the historic index performance.
Data won’t tell you whether to buy, sell or stay put. It can take the heat out of the headlines though and help you judge them against your own circumstances.
Sources
1. HM Land Registry – UK House Price Index
2. ONS – Consumer price inflation, UK: July 2026
3. ONS – CPI index, all items (2015=100)
Your home maybe repossessed if you do not keep up repayments on your mortgage.
The information contained within this article was accurate at the date of publication and is subject to change.
Get in touch
We’d love to hear from you.
By contacting Wealth Spring you confirm you have read our privacy notice, which can be found here.